
Thetaris Latest: Read all about professional financial modeling with Theta Suite and Monte Carlo Simulation.
Showing posts with label News. Show all posts
Showing posts with label News. Show all posts
2019-01-23
The Beauty of a DSL for Finance

2016-03-10
Theta Suite 3 available now
All kinds of structured financial products, especially Variable Annuities (VAs), can be described via ThetaML - the programming language for all Thetaris products including Theta Suite.

With the brand new developed Java backend ThetaML Compiler the product development of VAs will be even more simplified. Furthermore, existing VAs can easily be migrated in ThetaML, enabling a simplified data flow within server components.
In detail the ThetaML Compiler
- generates standalone Java classes (no Matlab required),
- minimalizes the initialization time,
- no re-compilation after input parameter change and
- supports simplified ThetaML language.
The second component ThetaML for Java developers offers
- full integration into Java IDE,
- full integration into Eclipse Debugging framework,
- convenient JAVA API and
- on the fly code generation.
Both components can be provided as Plug-In for the Java developer enviroment (e.g. Eclipse).
For more information, please follow the link: http://www.thetaris.com/thetasuite/
2014-12-12
Theta Suite Release Fall 2014 is available now
Theta Suite 2.3: Concentration on speed

- A new release of Thetaris' flagship product is now available. Theta Suite allows valuation, hedging and risk management of any financial contract. The focus lies on exotic structures, especially Variable Annuities.
For this release, besides many minor improvements, Thetaris focused on minimal initialization time and significant speed-up during aggregation processes. Furthermore the newest version of Theta Suite is now fully compatible with the Matlab 2014a. So it supports all Matlab versions since 2007b.
A new feature is the integration of a very efficient variance reduction technique. This technology allows running a simulation with only about one tenth of the scenarios while keeping the accuracy.
For more information please follow the link: http://www.thetaris.com/thetasuite/
Press release: Who is happy in the finance community?
Thetaris developed a crowdsourcing platform, that gives the answer.
 Shortly before years’ end, Thetaris asks the finance community for their input regarding the economic and financial expectations for 2015 (please see: who-is-happy.com). How happy are you with job, career, work, infrastructure. What are your expectations for economic and financial development in different regions of the world. It's time to sum up sector trends.
Thetaris, a provider of cutting-edge modeling solutions for easy structuring exotics, developed this easy to use crowd-sourcing platform. The site promises an entertaining interview process with instant feedback.
Crowd answers can be immediately matched against your own. The platform is completely anonymous, intuitive to use and comes with a modern design. Reports show the wisdom of the finance crowd for every topic and gives the user the ability to explore the data of all users in an analytics dashboard. Examples for what the users are able to investigate immediately include
- expectations for growth of the world economy in 2015 by Europeans vs Americans vs Asians.
- amounts of bonuses for senior level in Russia vs Europe vs China,
- career expectations of male vs female juniors in Europe,
- personal allocation of financial assets of finance professionals and
- many other topics.
2014-01-07
New Thetaris Research in Open Journal of Statistics
High-Dimensional Regression on Sparse Grids Applied to Pricing Moving Window Asian Options
Author(s)
Stefan Dirnstorfer, Andreas J. Grau, Rudi ZagstABSTRACT
The pricing of moving window Asian option with an early exercise feature is considered a challenging problem in option pricing. The computational challenge lies in the unknown optimal exercise strategy and in the high dimensionality required for approximating the early exercise boundary. We use sparse grid basis functions in the Least Squares Monte Carlo approach to solve this “curse of dimensionality” problem. The resulting algorithm provides a general and convergent method for pricing moving window Asian options. The sparse grid technique presented in this paper can be generalized to pricing other high-dimensional, early-exercisable derivatives.KEYWORDS
Sparse Grid; Regression; Least-Squares Monte Carlo; Moving Window Asian OptionLink
S. Dirnstorfer, A. Grau and R. Zagst, "High-Dimensional Regression on Sparse Grids Applied to Pricing Moving Window Asian Options," Open Journal of Statistics, Vol. 3 No. 6, 2013, pp. 427-440. doi: 10.4236/ojs.2013.36051.
2013-10-22
Theta Proxy XL works with FinAnSu
Theta Proxy XL is optimized for FinAnSu: A library for free real-time data acquisition in MS Excel. That means, people can try Theta Proxy XL with free real-time data and without the need to link into Bloomberg or tompson reuters.
2013-04-02
Functions in ThetaML
Many users asked for the introduction of function call into ThetaML. Since today, we provide a test release of Theta Suite version 2.4 together with the new function syntax. Besides the usual function concept, ThetaML functions also support function handles and partial evaluation with model time sensitive default values for some parameters. You will be surprised how much this can simplify your coding.
2013-01-30
Theta Proxy XL on c't software CeBIT - DVD Edition
As in previous years, some 2013 issues of the c't magazine include a covermount DVD-ROM. The DVD-ROM that will be in c't issue 6/2013 (CeBIT edition) features a hand-selected collection of free- and shareware programs as well as fully registered versions. This compilation includes software related to "science and technology" as well as "office workflows".

Theta Proxy XL, the Thetaris Excel Add-in software that accelerates the performance of complex Excel functions, such as user-defined functions (UDF) for Monte-Carlo simulation will be featured on the DVD and described in the c't magazine.
Please see also: http://www.thetaris.com/thetaproxy

We are happy and proud, that the c't magazine - one of the most important and widest-circulated software magazines in Germany - selected Theta Proxy XL for this DVD edition, which is issued in parallel to the CeBIT 2013, the world's largest trade fair showcasing digital IT and telecommunications solutions for home and work environments.
2012-12-20
Merry Christmas and a Happy New Year
The Thetaris team wishes all of you Merry Christmas and all the best for 2013.

We would like to thank all our customers and partners for your support, loyalty and feedback and are looking forward - together with you - to new challenges and ambitious projects in the next year.
See you!
Your Thetaris Team
2012-12-10
OpenGamma
Thetaris wants to call your attention to a new player in the financial software business we're very excited about: OpenGamma. Already recognized as a "firm of the future" by Risk Magazine, OpenGamma and its unified system for front-office and risk calculations is the latest buzz in the financial services industry. Especially interesting for our customers are its portfolio and the market data management capabilities.

The platform software is based on modern design principles and gets delivered as open source - notwithstanding full commercial support. Custom commercial components are also available and the platform's openness fosters integration with and extension by specialized data or technology providers. As such OpenGamma is a perfect match for Thetaris and its cutting-edge technologies and financial know-how.

A prototype for ThetaML integration with OpenGamma is already complete. We like the professional yet open mindset of the OpenGamma folks. As a matter of fact, we've already made first contributions back to the platform's official GitHub repository. We think the financial community can benefit a lot by joining up to improve this standards-based platform and create even better solutions for customers.
2012-10-31
Theta Suite - The Financial Simulation Tool - Free for Academics
Thetaris provides academic users free access to our Monte-Carlo
simulation software - Theta Suite, together with full technical support. By
offering a free academic license we want you and your colleagues to enjoy all the benefits which so far only industry practitioners have
experienced.
Theta Suite comes in two versions: Theta Suite XL is a stand-alone version which allows you to perform simulations in Excel in a brand new fashion. Theta Suite Professional on the other hand is deeply integrated into Matlab, so one could call it the Monte-Carlo toolbox for Matlab. So if you already use Matlab in your academic work, this could be your version of choice.
2012-10-10
Get your free ebook copy of "ThetaML Handbook"
Stefan Dirnstorfer, Andreas J. Grau and Hongzhu Li present a comprehensive introduction into the language for financial modelling "ThetaML" - the handbook is now available as a free pdf-download.

Content: Besides a brief introduction into Theta Suite, this handbook serves a complete reference on ThetaML. The book starts with a summary of the language features, followed by a chapter on ThetaML language syntax. The ThetaML type system, interfaces and workflows are detailed in later chapters. There are many code examples to help understand the language commands and functions. Two tutorials further apply ThetaML to pricing and hedging financial contracts, especially options. The final chapter offers many tips and tricks for more efficient use of ThetaML in financial settings. All examples are ready for testing and evaluation in Theta Suite using MC Simulation.
2012-07-11
Simple and transparent usage of Monte-Carlo simulations in Excel
Thetaris releases Theta Suite XL, an innovative Monte-Carlo toolbox for Microsoft Excel
Thetaris, a world-leading provider of modeling solutions for the financial sector, supports Excel analyses based on the Monte-Carlo simulation method with its new solution Theta Suite XL. Typical weak areas of Microsoft Excel like low performance and usability during the calculation of a large number of scenarios no longer pose a problem: Theta Suite XL defines the original simulation model outside of Excel, using the simple coding language ThetaML, which has been developed especially for Monte-Carlo simulations. Via the so-called Excel-Bridge, an Excel add-in, models can be configured and evaluated outside Microsoft Excel.
2012-06-25
Thetaris at MATLAB Computational Finance Conference
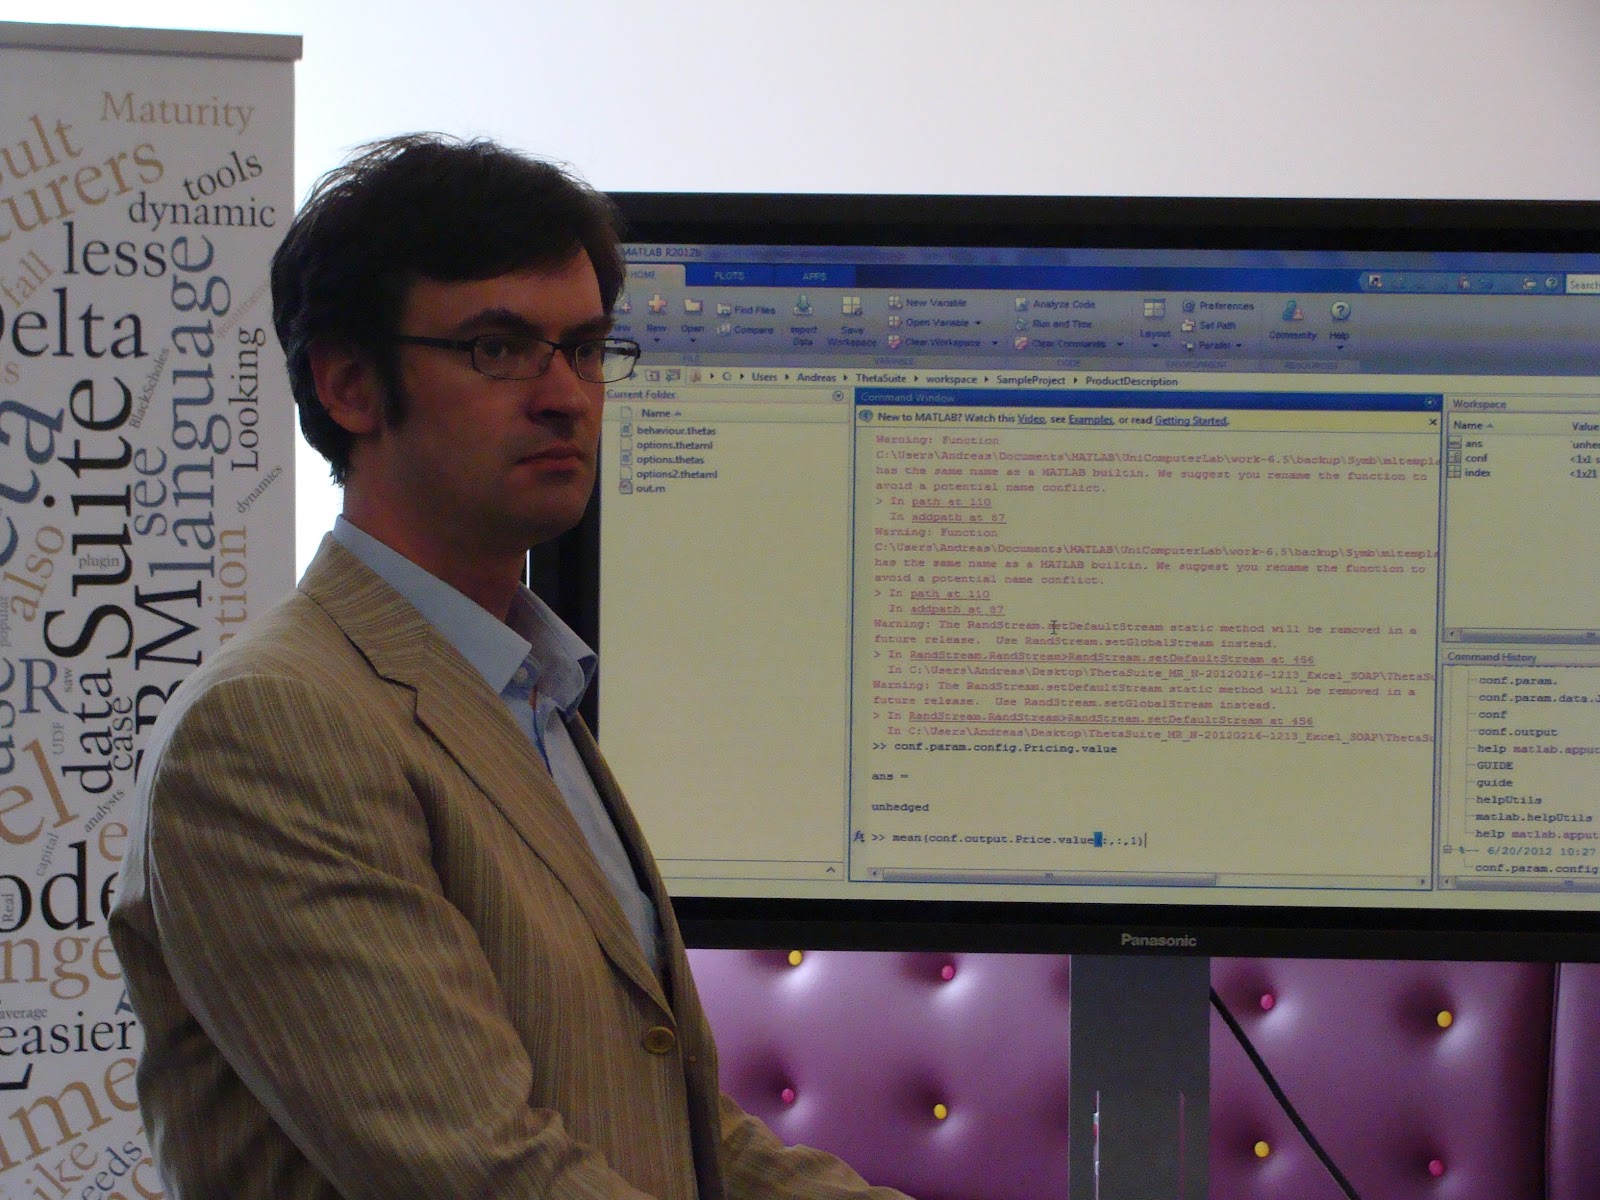
Thetaris presented ThetaSuite at the MATLAB Computational Finance Conference in London
19 - 20 June 2012
“An interested
audience, intensive talks with customers and developers of Mathworks and a very
positive feedback on our product presentations”, resumed Dr. Andreas Grau the
two exhibition days at the MATLAB CF Conference.
 |
| Dr. Stefan Dirnstorfer at the Thetaris booth |
2012-05-24
Cover Story at RISIKOMANAGER
Thetaris article is cover story of German finance magazine RISIKO MANAGER Issue 11/2012

The article „Markt-Risikomanagement
für Asset Manager“, written by
Dr. Andreas Grau, CEO and Dr. Stefan Dirnstorfer – COO of the Thetaris GmbH - is the main topic of the actual RISIKO MANAGER issue 11.2012 (www.risiko-manager.com).
The article
describes the basic necessity of professional risk management not
only for investment banking but also in the area of asset management. Furthermore it points out that the investment
in a solid and mature risk management solution is cheaper and easier to
implement than public opinion suggests. At the end the user – specifically a asset
manager – will eventually not recognize that he is still working with his used calculation tool.
Please find an extract of the article online here - the complete article can be ordered in
written form on the RISIKO MANAGER
website
2012-05-07
ThetaML Handbook available now in print!
Stefan Dirnstorfer, Andreas J. Grau and Hongzhu Li present a comprehensive introduction into the language for financial modelling, ThetaML: "ThetaML Handbook" has arrived in stores:

If you are a customer with a valid Theta Suite license, you will receive your complementary copy in a few days.
For purchase see your local book store, or e.g.
www.amazon.de/ThetaML-Handbook-Stefan-Dirnstorfer/
www.amazon.co.uk/ThetaML-Handbook-Stefan-Dirnstorfer/

For purchase see your local book store, or e.g.
www.amazon.de/ThetaML-Handbook-Stefan-Dirnstorfer/
www.amazon.co.uk/ThetaML-Handbook-Stefan-Dirnstorfer/
Besides a brief introduction into Theta Suite, this handbook serves a complete reference on ThetaML. The book starts with a summary of the language features, followed by a chapter on ThetaML language syntax. The ThetaML type system, interfaces and workflows are detailed in later chapters. There are many code examples to help understand the language commands and functions. Two tutorials further apply ThetaML to pricing and hedging financial contracts, especially options. The final chapter offers many tips and tricks for more efficient use of ThetaML in financial settings. All examples are ready for testing and evaluation in Theta Suite using MC Simulation.
2012-04-19
Risk Managment: Investment Bank Solution for Asset Manager

Maintainable, transparent models replace in-house development based on Excel-VBA
Thetaris, a world-leading provider of modeling solutions for the financial sector, releases Theta Suite Portfolio Market Risk Management. This novel risk management software solution offers asset managers and small to medium sized insurance companies the flexibility and performance which so far has only been achieved with applications tailored to major financial institutions.
2012-03-01
Thetaris Theta Proxy XL in c't Magazine 6/2012
There is an article about Theta Proxy XL in the current c't Magazine 06/2012. Theta Proxy XL was added to the heise Software Repository.
2012-02-20
Real-Time Spreadsheet Calculations
Thetaris Theta Proxy XL provides high performance computing in MS Excel
Thetaris presents Theta Proxy XL, an Excel Add-in software that accelerates the performance of complex Excel functions, such as user-defined functions (UDF) for Monte-Carlo simulation. This software is targeted at all Excel users for whom fast calculation of formula results is essential. This includes traders at banks and other financial institutions who have to react instantly to price changes and, therefore, need real-time calculations. Theta Proxy XL calculates the values of Excel cells containing, for example, complex financial functions in a fraction of a second.
2012-01-22
Thetaris Website Relaunch
Finally, we got a new website!! Visit us now on the main page Thetaris.com AND the brand new dedicated sites for our products Theta Suite and Theta Proxy. Additionally, we launched a website for news, events and - your comments: blog.thetaris.com. Theta Suite allows precise modeling of structured products and pricing using Monte Carlo Simulation. Theta Proxy XL speeds-up MS Excel User Defined Functions (UDF) e.g. for High-Frequency Trading with Low Latency.
Subscribe to:
Posts (Atom)