2012-10-31

Theta Suite - The Financial Simulation Tool - Free for Academics


Thetaris provides academic users free access to our Monte-Carlo simulation software - Theta Suite, together with full technical support. By offering a free academic license we want you and your colleagues to enjoy all the benefits which so far only industry practitioners have experienced.

Theta Suite comes in two versions: Theta Suite XL is a stand-alone version which allows you to perform simulations in Excel in a brand new fashion. Theta Suite Professional on the other hand is deeply integrated into Matlab, so one could call it the Monte-Carlo toolbox for Matlab. So if you already use Matlab in your academic work, this could be your version of choice.

2012-10-22

PRMIA Event on Discounting after the Financial Crisis

The PRIMIA Munich Chapter invited its community to a meeting with Dr. Roland Stamm, Deutsche Pfandbriefbank, and his talk about the "Discounting and Curve Construction Since the Beginning of Financial Crisis 2007" on the 18th of October 2012.


In the aftermath of the financial crisis one major pillar of financial engineering and risk-free pricing has disappeared: Interest rates for lending and borrowing money can no longer be assumed to be more or less equal. When spreads between lending and borrowing widened after 2007, financial engineers realized they had to look for new approaches to product pricing.

Even relatively simple products like basis swaps turned into a big challenge. Before the crisis, swaps could be priced very objectively from a known interest rate curve. After the crisis counter party risks started to play a major role. This not only affects the valuation of hedging instruments but also the valuation of collateral that nowadays has to be provided and actively updated during a product's life cycle.

Trading swaps between banks also has become a problem. Very often it is simply not possible to agree on one price. Financial engineers are just starting to establish theories to cope with this complicated world. Before the crisis structured products were challenging. Now, simple products can pose an even bigger challenge.


2012-10-18

Eclipse Finance Day & Eclipse Con

Eclipse has grown from a simple open source Java development environment into a platform for large-scale enterprise applications. The Eclipse Finance Day on Oct. 16th in Zurich showed impressive examples of recent developments and usage of eclipse technology in financial institutions. Eclipse Con on Oct. 23rd in Ludwigsburg will be the next opportunity for exchanging experiences and ideas.

2012-10-10

Get your free ebook copy of "ThetaML Handbook"

Stefan Dirnstorfer, Andreas J. Grau and Hongzhu Li present a comprehensive introduction into the language for financial modelling "ThetaML" - the handbook is now available as a free pdf-download.


Clownfish on ThetaML Handbook Cover
Please follow the link http://www.thetaris.com/support/download-of-handbook and just download the E-book (pdf-file). 


Content: Besides a brief introduction into Theta Suite, this handbook serves a complete reference on ThetaML. The book starts with a summary of the language features, followed by a chapter on ThetaML language syntax. The ThetaML type system, interfaces and workflows are detailed in later chapters. There are many code examples to help understand the language commands and functions. Two tutorials further apply ThetaML to pricing and hedging financial contracts, especially options. The final chapter offers many tips and tricks for more efficient use of ThetaML in financial settings. All examples are ready for testing and evaluation in Theta Suite using MC Simulation. 


2012-07-11

Simple and transparent usage of Monte-Carlo simulations in Excel

Thetaris releases Theta Suite XL, an innovative Monte-Carlo toolbox for Microsoft Excel

Thetaris, a world-leading provider of modeling solutions for the financial sector, supports Excel analyses based on the Monte-Carlo simulation method with its new solution Theta Suite XL. Typical weak areas of Microsoft Excel like low performance and usability during the calculation of a large number of scenarios no longer pose a problem: Theta Suite XL defines the original simulation model outside of Excel, using the simple coding language ThetaML, which has been developed especially for Monte-Carlo simulations. Via the so-called Excel-Bridge, an Excel add-in, models can be configured and evaluated outside Microsoft Excel.

2012-06-25

Thetaris at MATLAB Computational Finance Conference

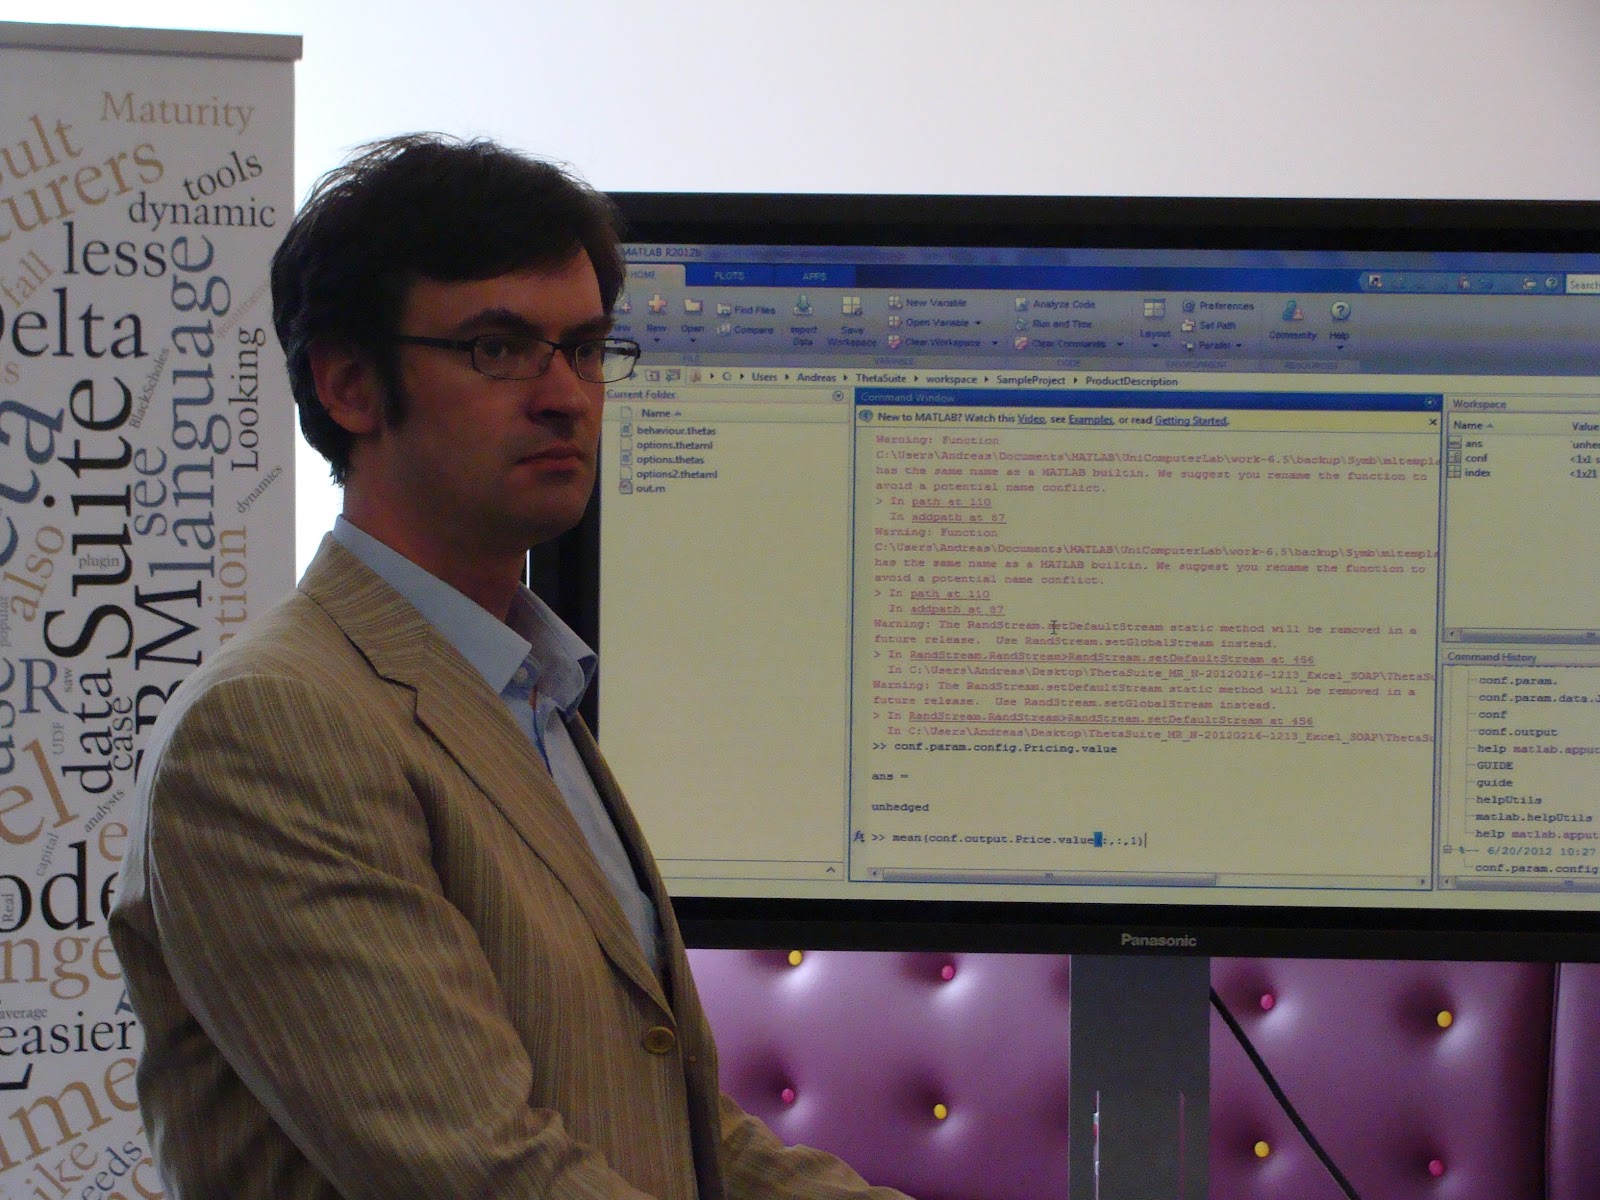
Thetaris presented ThetaSuite at the MATLAB Computational Finance Conference in London 

19 - 20 June 2012


“An interested audience, intensive talks with customers and developers of Mathworks and a very positive feedback on our product presentations”, resumed Dr. Andreas Grau the two exhibition days at the MATLAB CF Conference.
Dr. Stefan Dirnstorfer at the Thetaris booth

2012-05-30

Thetaris at MATLAB Computational Finance Conference


Thetaris at the MATLAB  Computational Finance Conference
in London

19 – 20 June 2012


Thetaris will join the MATLAB Computational Finance Conference as one of seven exhibitors taking place in London from 19 to 20 June 2012.


As Thetaris uses MATLAB®’s power and flexibility to build tailored solutions for finance professionals the MATLAB Computational Finance Conference in London is an ideal event for demonstrating how Thetaris customizes MATLAB enabling quants and actuaries to obtain an efficient workplace which realizes computer aided finance - from prototyping to production. A good overview about this approach shows our publication Theta Suite – RiskManager Solution for Asset Manager

The MATLAB Computational Conference is strongly focused on the usage of MATLAB® to develop risk, trading, investment management and insurance applications. Keynote speeches, customer presentations and Master class tutorials will underline this approach.